ESG in the Aerospace and Defence Sector
An Emerging Compliance Frontier
Reading Time
5 min
Article Sections
5
Share Links
3
On This Page
Article Section
The Regulatory Landscape Is Splitting in Two
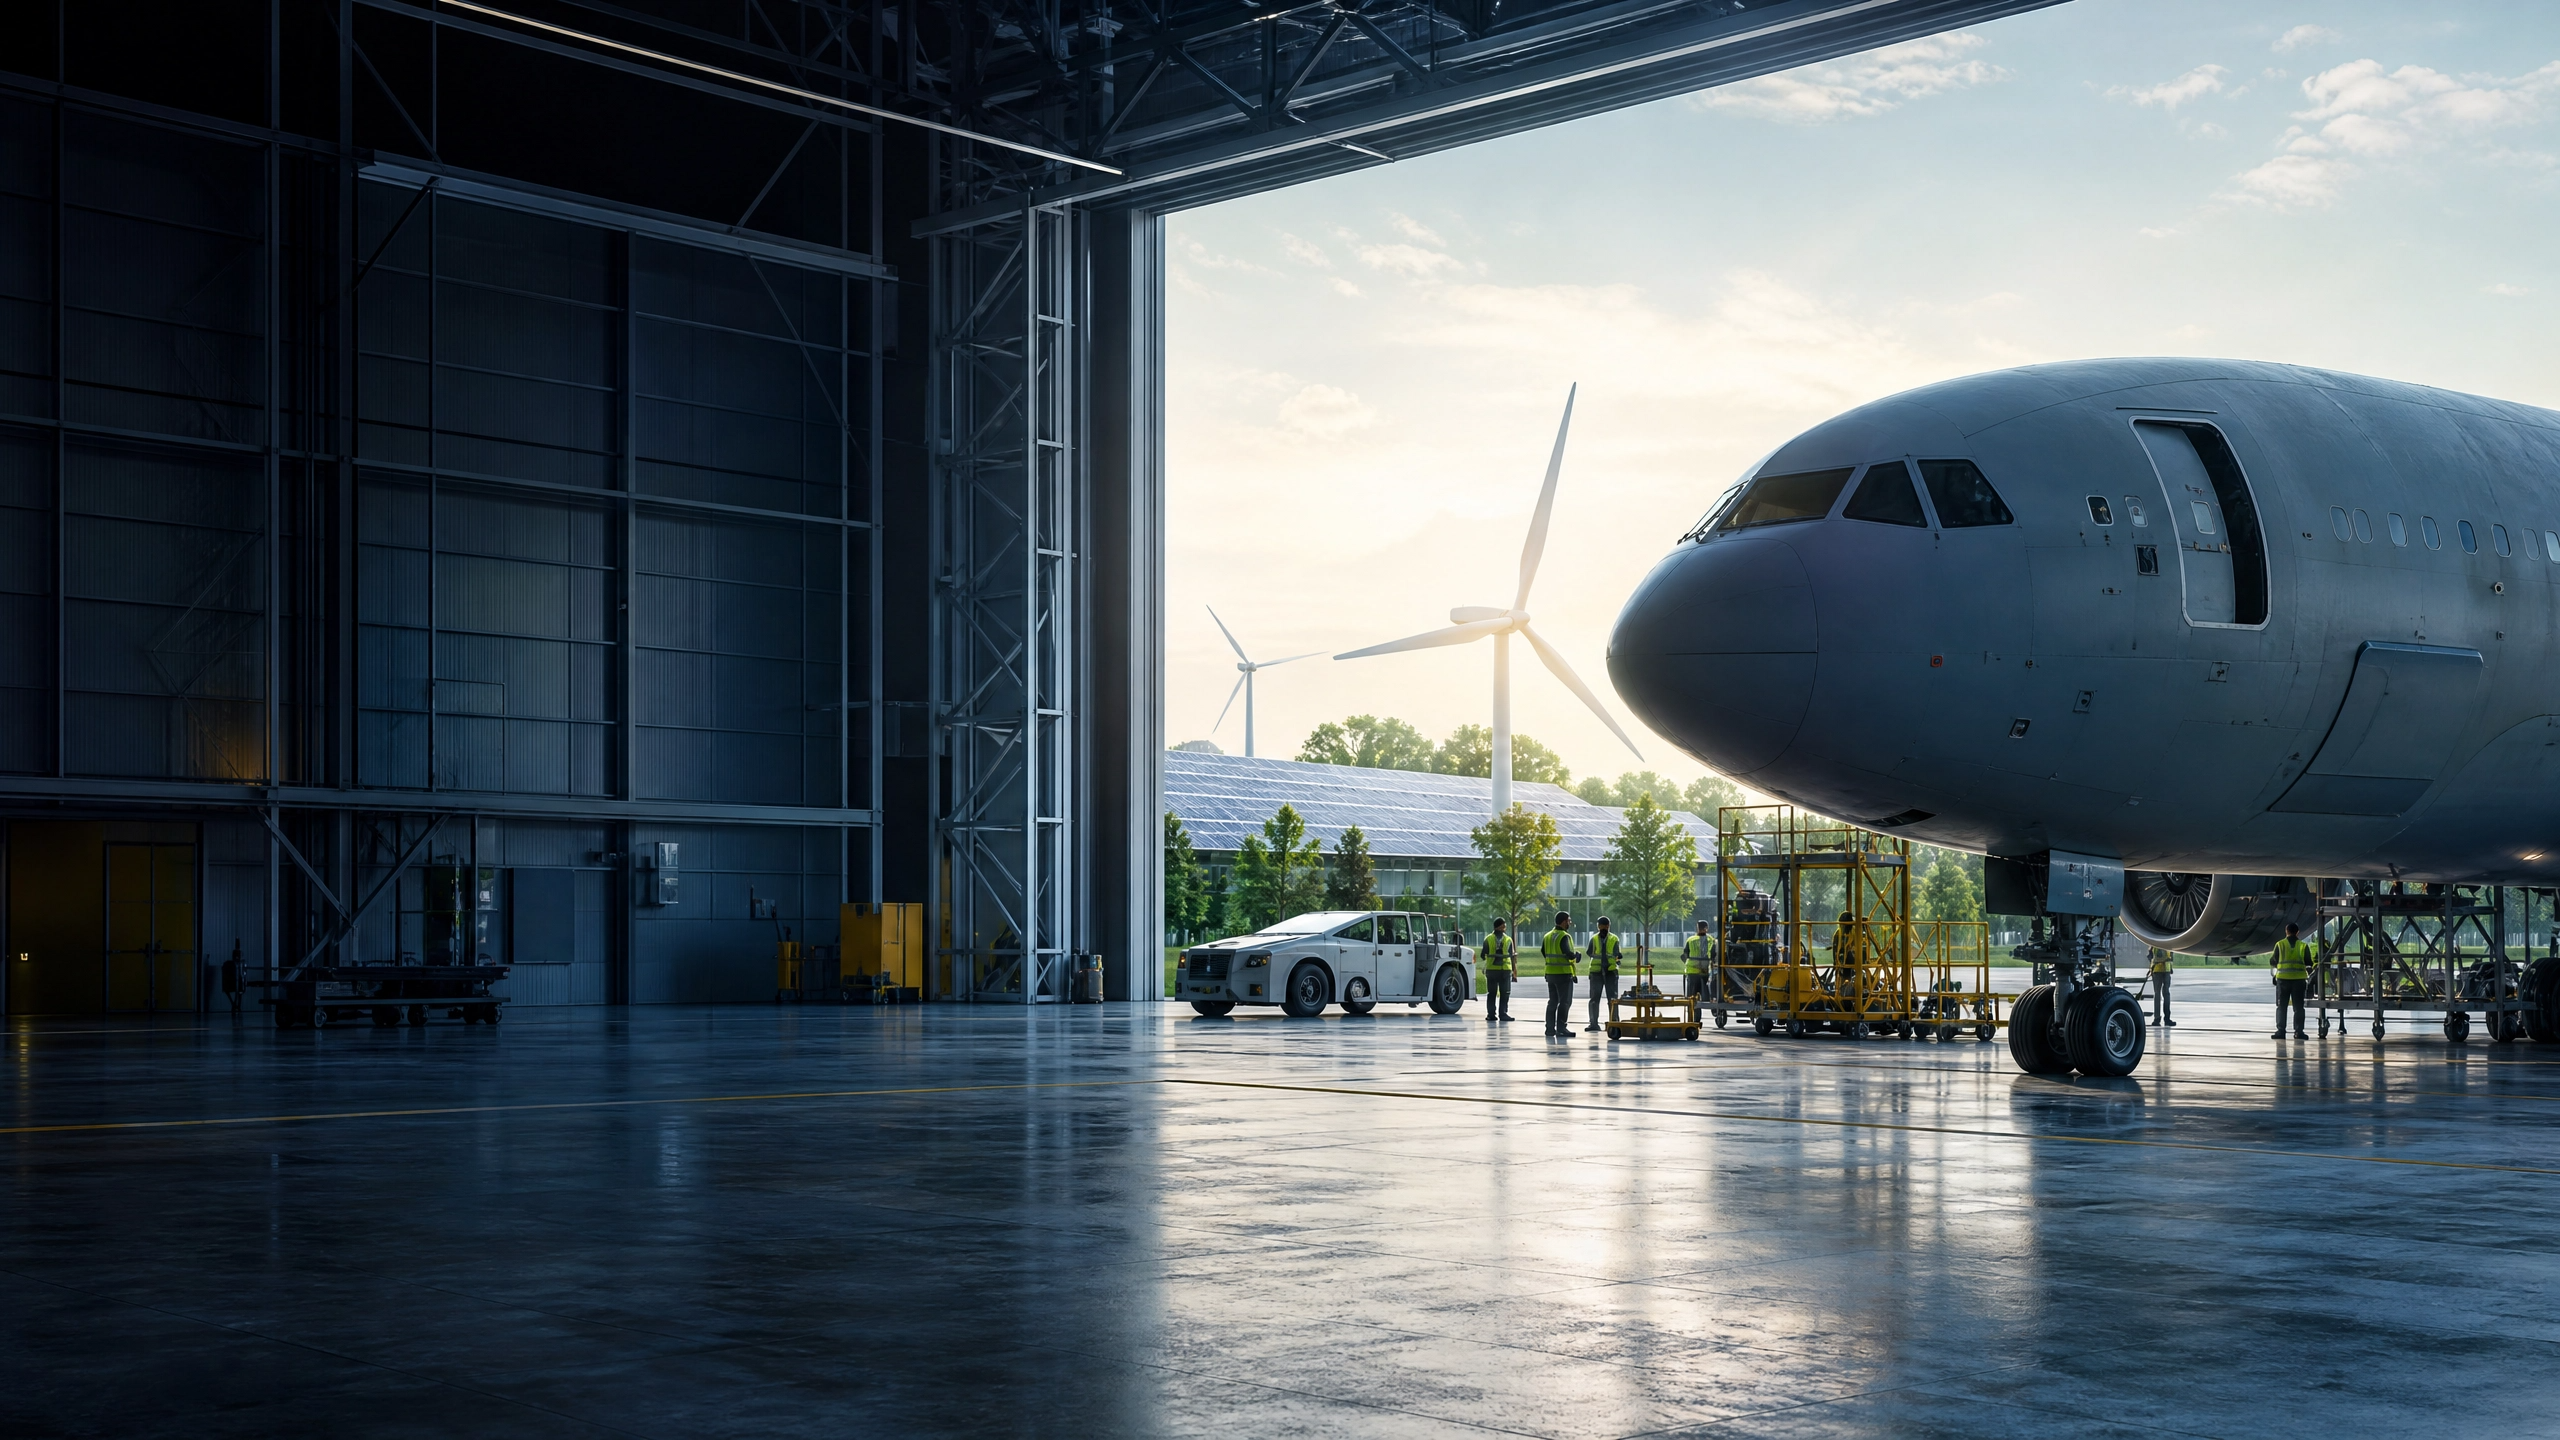
Commercial aviation and military operations sit under very different regulatory regimes despite contributing to the same emissions total. Commercial aviation, covered by IATA's net zero 2050 pledge and ICAO's CORSIA offsetting scheme, faces escalating requirements: the EU's ReFuelEU Aviation rule mandates a 2 % sustainable aviation fuel blend at EU airports from 2025, rising to 70 % by 2050, while the EU Emissions Trading System phases out free carbon allowances by 2026.
Defence activity operates under a different logic. Military emissions are largely exempt from binding international reporting, and less than 10 % of true military emissions reach the UNFCCC. NATO's Climate Action Plan introduces voluntary GHG measurement for member militaries, and the EU Defence Agency is developing standardised disclosure protocols, but neither carries the force of CSRD or ReFuelEU.
At the same time, defence manufacturing is excluded from the EU Green Taxonomy, cutting it off from a large pool of sustainable finance even as Europe's Defence Readiness Omnibus signals intent to mobilise up to 800 billion euros for the sector. The regulatory map, in short, is being drawn unevenly, and companies operating across both commercial and defence lines have to navigate two different compliance clocks at once.
Article Section
Why the Compliance Gap Matters More Than It Looks?
The military emissions blind spot
Military activity is estimated to account for 5.5 % of global greenhouse gas emissions, which would make it the fourth largest emitter in the world if counted as a country. Less than 10 % of that figure is disclosed to international bodies, and Scope 3-plus emissions from combat operations, infrastructure destruction and post-conflict reconstruction remain entirely unquantified. This is not a data gap regulators are likely to tolerate indefinitely. As ESG rating agencies begin factoring estimated military emissions into sector-adjusted scores, companies with no internal measurement capability will find themselves rated on assumptions rather than disclosed data, a position with obvious downside risk.
The taxonomy paradox
Defence manufacturing sits outside the EU Green Taxonomy, which limits access to taxonomy-aligned sustainable finance for defence-specific activities. At the same time, clarified SFDR rules make defence eligible for sustainability-linked funds, and the Defence Readiness Omnibus is pushing hundreds of billions of euros toward the sector. The result is a structural mismatch: capital ambition is rising faster than the governance frameworks needed to direct it responsibly, and companies that build credible ESG reporting now will be better positioned to capture that capital as the rules catch up.
Critical minerals as a compliance risk, not just a procurement one
Rare earths, cobalt, lithium and titanium sit at the core of modern aircraft and defence systems, and China controls roughly 60 % of rare earth production and 90 % of refining, while the Democratic Republic of Congo supplies 68 % of global cobalt. Artisanal cobalt mining in the DRC involves more than 40,000 children, a human rights exposure increasingly scrutinised alongside supply concentration risk. The US NDAA now mandates rare earth independence from adversary nations by 2035, which means responsible sourcing has moved from a corporate responsibility talking point to a national security and procurement requirement.
The financial cost of getting governance wrong
Boeing's 737 MAX crisis and the subsequent Alaska Airlines incident destroyed more than 50 billion dollars in value, a reminder that governance failures in this sector carry outsized financial consequences. On the other side of the ledger, aerospace and defence companies with strong ESG governance show 2 to 5 %age points lower operating costs than laggards, and those with SBTi-validated targets are accessing financing at 20 to 50 basis points below conventional rates. The financial case for credible ESG governance is no longer theoretical.
Article Section
What Leaders Should Do Now
Build Scope 1, 2 and 3 inventories ahead of the mandate
Companies that wait for a regulatory deadline to complete comprehensive Scope 1, 2 and 3 GHG inventories will be building reporting infrastructure under time pressure. Sector-specific methodologies already exist, and early movers gain a head start on the data quality investors and regulators increasingly expect.
Treat the military emissions gap as a matter of time, not permanence
NATO, the EU Defence Agency and rating agencies are all moving in the same direction: toward mandatory disclosure of military emissions. Companies with defence exposure should build internal measurement capability now rather than waiting for the UNFCCC or national regulators to force the issue.
Elevate critical mineral sourcing to board-level governance
Given the concentration risk in rare earth and cobalt supply chains, sourcing decisions carry both human rights and national security implications. This warrants board-level oversight rather than treatment as a routine procurement matter.
Use credible disclosure as a financing lever
SBTi validation and transparent ESG-linked executive pay are not just reporting exercises. They are increasingly priced into the cost of capital, and companies that treat them as strategic tools rather than compliance checkboxes will out-compete peers on financing terms.
Article Section
Conclusion
ESG compliance in aerospace and defence is no longer confined to sustainability reports. It is beginning to shape access to capital, government contracts and financing costs, and the sector's biggest disclosure gap, military emissions, is closing faster than many companies have prepared for.
The companies that treat ESG infrastructure as core to their compliance and financing strategy, rather than as a parallel reporting exercise, will be the ones best positioned when today's voluntary frameworks become tomorrow's binding requirements.
Article Section
Frequently Asked Questions
Why does military activity remain largely outside ESG emissions reporting?
Military emissions are largely exempt from binding international reporting frameworks such as the UNFCCC, with less than 10 % of true military emissions currently disclosed.
Is defence manufacturing eligible for EU sustainable finance?
Defence manufacturing is excluded from the EU Green Taxonomy but has gained eligibility for SFDR-regulated sustainable finance under recently clarified rules.
What financial advantage do ESG leaders in aerospace and defence see?
Companies with SBTi-validated targets access financing at 20 to 50 basis points below conventional rates and report 2 to 5 %age points lower operating costs than laggards.
Why are critical minerals a governance issue for the sector?
Rare earth and cobalt supply chains are highly concentrated in China and the Democratic Republic of Congo, creating both national security exposure and human rights risk that boards are now expected to oversee directly.
What regulatory changes should aerospace and defence companies prepare for next?
Expect the military emissions reporting gap to narrow as NATO, the EU Defence Agency and ESG rating agencies push toward mandatory disclosure, alongside escalating ReFuelEU SAF blending requirements through 2050.
Keep Reading
Related Blogs
Governance
The Turning Point for ESG in India Is Here
How ESG Reporting Is Transforming Corporate Accountability
Read more
Governance / Investor Relations
Five ESG Metrics Every Investor Pitch in India Should Now Include
Most Still Don't Know
Read more
Governance / Risk
ESG Controversies and Reputational Risk
How One Bad News Story Can Move Your Sustainalytics Score
Read moreNext Step
Ready to turn ESG complexity into strategic advantage?
Talk to ESG Astraa about disclosures, climate strategy, governance controls, and execution support for your team.